Tropical destinations

Tropical destinations

Tropical Destinations: A Practical Guide to Modern Warm-Weather Travel

I’ve spent the better part of a decade chasing warm fronts and humid air, and as a guy who’s logged thousands of miles across three continents, I can tell you why some getaways feel effortless while others drain your savings and sanity. If you’re reading this, you probably already know the drill: booking flights during peak season, fighting through resort crowds, and realizing halfway through that the brochure photos lied about the beachfront. The reality of modern travel is that location matters, but so does timing, infrastructure, and how well you understand what you’re actually buying into.

Understanding the Shift in Modern Tropical Vacation Standards

Let’s break down the terminology first. When experts talk about equatorial travel zones, they’re not just pointing at a map and hoping for palm trees. We’re dealing with microclimates, seasonal monsoon shifts, and increasingly regulated coastal zones. Back in the nineties, you could show up in a coastal town with a backpack and find a decent room for twenty bucks. Today, sustainable tourism mandates, reef protection laws, and carbon offset requirements have completely restructured the industry. The dynamics have shifted from mass exploration to curated, low-impact experiences. That’s why a simple getaway now requires research into rainfall patterns, local conservation fees, and whether the infrastructure can handle your travel style without collapsing under overtourism. As of 2026, regional authorities in both the EU and USA have tightened entry protocols for protected marine areas, making advance planning non-negotiable.

Planning Routes to Tropical Places to Go for Different Travel Styles

The biggest mistake people make is treating every warm coastline the same. Humidity varies wildly between regions, and flight connections dictate your actual downtime. I always recomend mapping out the shoulder seasons first. You’ll pay less, deal with fewer tourists, and still catch decent weather. The real value comes from aligning your itinerary with regional climate windows instead of chasing holiday weekends. Here’s a quick breakdown of how modern travelers approach the process:

  • Check historical precipitation data instead of relying on marketing glossaries
  • Prioritize direct flight routes to cut layover fatigue and baggage risks
  • Verify reef and wildlife conservation fees before booking transfers
  • Book accomodations outside the primary tourist corridor for authentic pricing
  • Secure comprehensive travel insurance that covers weather disruptions

Mapping Out Essential Tropical Places to Visit in the Current Decade

Below is a straightforward comparison of regions that consistently deliver value, safety, and manageable crowd levels. I’ve pulled data from recent tourism reports and climate tracking agencies to keep this grounded in reality rather than influencer hype.

Region Peak Season Average Rainfall (Inches) Visitor Focus
Caribbean Windward Islands Dec–Apr 3.2 Sailing, reef diving, cultural heritage
Central American Pacific Coast Nov–Mar 2.8 Surfing, eco-lodges, wildlife tracking
Southeast Asian Archipelagos Nov–Feb 4.1 Island hopping, culinary tourism, temple routes
South Indian Ocean Territories Jun–Sep 3.5 Conservation tourism, low-density resorts

“The coastlines we explore today are managed differently than the unregulated shores of the past. Respecting local conservation frameworks isn’t a restriction, it’s the only way these ecosystems survive for the next generation.”

How to Secure the Best Tropical Vacation Spots Without the Algorithmic Crowds

Everyone wants the same five beaches, which is exactly why those beaches lose their charm. I’ve learned to bypass the algorithim-driven hotspots by tracking regional flight schedules and local event calendars. When a major festival hits a coastal town, prices spike and quiet zones get flooded. The workaround is simple: target the two-week window right after peak season ends. You’ll still get warm water, but the service staff actually has time to care about your experience. For verified regional data and updated entry requirements, I usually reference official tourism boards like this UNWTO resource center. Another passive reference is the NOAA tropical ecosystem archive.

Keep your expectations grounded, pack for humidity instead of sunshine, and stop treating every warm map coordinate like a guaranteed paradise. The right destination will align with your pace, not the other way around.
How do insurance companies make money?

How do insurance companies make money?

How Do Insurance Companies Make Money?

I have spent over a decade tracking financial models in this sector, and the truth behind carrier profitability rarely matches public perception. Most folks assume the business runs on collecting monthly checks and hoping claims stay low. When you actually map out how do insurance companies make money, the reality splits into two distinct engines: disciplined underwriting and strategic capital deployment. It is a highly calculated balancing act that has evolved from nineteenth century maritime ledgers into algorithmic risk ecosystems.

The Core Revenue Mechanics

How Do Insurance Companies Make Money

At its foundation, the industry relies on probability mathematics and large scale risk aggregation. Acturaries crunch decades of mortality, accident, and climate data to set premiums that statistically exceed expected payouts. The gap between collected funds and paid claims creates the initial margin. Over the last twenty years, telematics and behavioral tracking have completely rewritten pricing accuracy, allowing carriers to segment policyholders with surgical precision.

Understanding Premiums and Risk Pooling

Premiums are not profit. They represent advance payments for a contractual promise. When thousands of policyholders pool their funds, the carrier assumes liability across a diversified base. This statistical smoothing prevents a single catastrophic event from wiping out reserves. Historically, pricing relied on broad demographic tables. Today, real time sensor data has narrowed the uncertainty gap, though the core principle of mutualizing exposure remains untouched.

Risk cannot be eliminated, only transferred and priced with mathematical rigor. The modern carrier survives by mastering that equation.

Investment Income: The Real Profit Driver

This is where actual wealth generation happens. Between collecting premiums and settling claims, carriers sit on massive cash reserves known as the float. That capital does not idle in a vault. It flows into government bonds, corporate debt, real estate, and private credit markets. In a high yield environment, investment returns routinely outpace underwriting profits. The combined ratio tracks operational health, but the investment spread dictates shareholder value. Back in the nineteen nineties, carriers leaned heavily on safe treasuries. Today, institutional portfolios incorporate structured credit and infrastructure debt to chase yield without breaching solvency thresholds.

Revenue Stream Function Volatility Profile
Net Premiums Earned Covers expected claims and overhead Low to Moderate
Investment Yield Generates profit from the float Moderate to High
Fee Based Services Administrative and risk consulting income Low

Where Do Insurance Companies Get Money

Beyond policyholder premiums, carriers tap into layered funding structures to maintain liquidity during stress periods. Reinsurance treaties transfer portions of catastrophic exposure to global capital partners, effectively purchasing a financial backstop. Capital market instruments like catastrophe bonds allow institutional investors to assume specific risk tranches in exchange for coupon payments. This ecosystem ensures that even during unprecedented loss years, balance sheets remain solvent. You can track current 2026 regulatory capital requirements and reserve adequacy metrics through official industry databases like NAIC regulatory portals.

Reinsurance and Capital Markets Explained

  • Proportional treaties split premiums and losses by a fixed percentage across partners
  • Excess of loss agreements trigger only when claims breach predetermined thresholds
  • Catastrophe bonds convert insurance risk into tradable securities for institutional portfolios

How Does Insurance Companies Make Money

The phrasing might sound slightly off, but the operational reality is razor sharp. Profitability hinges on controlling the loss ratio, optimizing acquisition costs, and maintaining a lean administrative expense structure. When underwriting discipline slips, investment income must compensate, which introduces market exposure into a traditionally defensive business. Carriers that thrive during economic downturns prioritize expense ratio compression and automated claims processing. Legacy manual underwriting has largely given way to algorithmic decision engines that evaluate risk in milliseconds.

Insurance Companies Make Money By…

…leveraging data asymmetry, enforcing policy exclusions, and reinvesting the float at scale. The modern playbook emphasizes retention over acquisition, using loyalty discounts and embedded coverage to stabilize cash flow. Dynamic pricing models adjust premiums based on real time risk signals, from driving behavior to property maintenance logs. This shift has fundamentally altered how carriers approach customer lifetime value, moving from transactional sales to continuous risk monitoring.

The industry no longer sells peace of mind. It sells calibrated risk transfer backed by quantitative precision.

The Shift from Legacy Models to Predictive Pricing

Decades ago, rate filings required months of manual review and actuarial guesswork. Today, machine learning pipelines process millons of claims records, weather patterns, and economic indicators simultaneously. This acceleration has compressed pricing cycles from quarters to days, allowing carriers to respond to emerging loss trends before they compound. The evolution from reactive indemnity to proactive loss prevention marks the most significant transformation in the sector since the industrial era. While regulatory frameworks lag behind technological velocity, the underlying mechanics remain anchored in statistical fairness and capital preservation.

Difference between personal property tax and real estate tax

Difference between personal property tax and real estate tax

Difference between personal property tax and real estate tax

I run a small advisory desk out of Austin, and after fifteen years of helping guys sort through county bills and business filings, I still watch people trip over the exact same phrasing every spring. You close on a house, open the assessor’s portal, and suddenly wonder why your statement looks nothing like your neighbor’s. The confusion stems from how local jurisdictions classify what you actually own. I break down the mechanics below so you stop guessing where your money goes and how the rates get calculated.

Property vs real estate tax

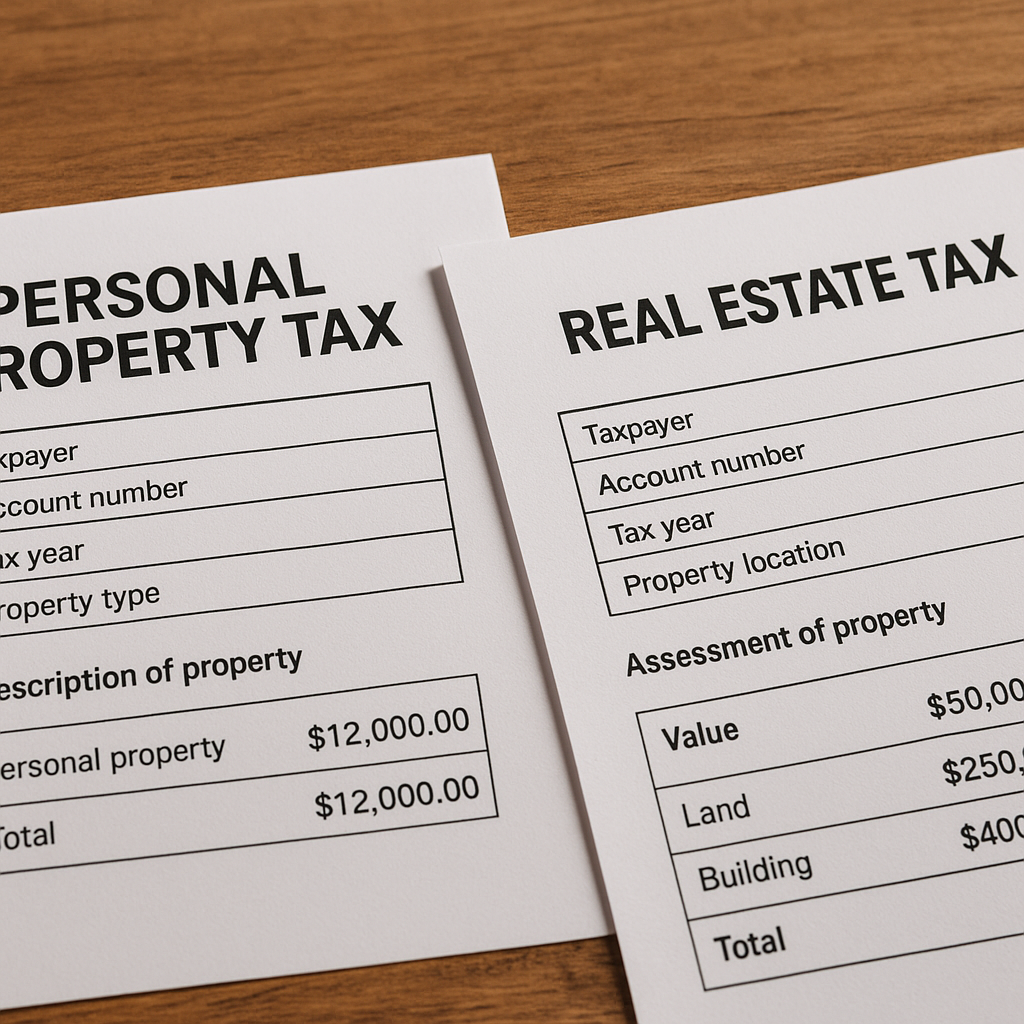
The phrasing sounds interchangable until you start reading municipal codes. In plain terms, the broader category covers anything a local government can levy a value-based charge on. Ad valorem systems measure worth at a specific snapshot date, then apply a local millage rate. Most counties separate movable items from fixed assets, which changes your rate, your appeal window, and your payment schedule. If you run a contracting business or lease heavy equipment, you will see a completely different billing cycle than your residential neighbors.

Personal property vs real property

When we talk about tangible holdings, the split comes down to mobility and attachment to land. Real property means the soil, structures permanently bolted to it, and fixtures that legally transfer with the deed. Personal property covers vehicles, machinery, inventory, and even certain leased assets depending on your state. Historically, this classification dates back to agrarian economies where land was the only measurable wealth. The Industrial Revolution forced assessors to track railroads and factory lines, and the digital shift added leased solar arrays, server racks, and fleet EVs to the taxable roll. That evolution explains why your county now asks for a separate declaration on office computers while your house gets a separate appraisal.

“The line between movable and fixed assets isn’t just legal jargon; it dictates which government office sends you the bill, how often they reassess, and what exemptions actually apply.” — State Tax Policy Review, 2025

Real estate tax vs property tax

Locally, officials often swap both phrases on the same form, but the accounting departments treat them differently. One targets immovable holdings exclusively, while the other functions as an umbrella term. If your municipality collects both, you might see two separate statements: one for your lot and dwelling, another for business equipment or recreational vehicles. The overlap creates genuine friction during audits because some jurisdictions fold the land levy into the general column, while others keep the ledgers strictly divided. You will notice this most clearly when buying out a commercial lease or transferring ownership of a family trust.

Classification Typical Examples Assessment Frequency
Land & Structures Houses, commercial buildings, permanent foundations Annual or biennial
Mobile & Business Assets Company vehicles, leased machinery, inventory Yearly declaration required

Is real estate tax the same as property tax

Technically, no, even though the phrasing gets swapped in casual conversation. The narrower term applies strictly to immovable assets, while the wider phrase encompasses everything from a tractor to a factory line. Over the last twenty years, remote work and decentralized supply chains forced assessors to adapt. Counties now track home office gear, mobile workstations, and cloud infrastructure leases that simply did not exist in traditional ledgers. That shift means your total obligation can change even if your square footage stays identical. You can track updated millage rates and exemption thresholds through official municipal portals like the federal guidance page, which cross-references state-level methodologies, or check regional compendiums such as the Census Bureau’s annual housing finance reports. Keep your purchase receipts and depreaciation scheduals organized for audit season, and always verify that assessor data matches actual renovations.

  • File movable asset declarations before the county deadline to avoid penalties.
  • Request exemption forms for primary residences, agricultural use, or veteran status.
  • Track depreciation values for equipment to lower future declarations.
  • Verify square footage and recent upgrades match public records.

Understanding how local offices categorize your holdings saves time when you navigate reassessments, appeal windows, and payment schedules. The system rewards documentation and penalizes assumptions, so I always recommend keeping a clean paper trail for anything you depreciate or transfer across fiscal years.